Understand your insurance before you need it.
Home insurance is the most common voluntary insurance: 84 per cent of respondents' households have it. Insurance matters also generate disputes – FINE received about 9,300 contacts in 2025, and 65% of them concerned insurance. For an entrepreneur, YEL insurance is compulsory, and for an employer paying wages, TyEL and accident insurance; the YEL and TyEL contribution in 2026 is on average 24.4%. The page explains impartially which insurances are compulsory and how to appeal a compensation decision; we do not sell, compare or recommend insurance or companies.
Insurance Radar tells you impartially which insurance policies are mandatory, what home insurance typically covers and how to appeal a compensation decision. The page does not sell or compare insurance.
- Households and motorists
- Entrepreneurs and employers: YEL, TyEL and accident insurance
Calculator
Calculator
Calculators on their own pages: Deductible calculator · Entrepreneur's mandatory insurance calculator 2026 · All calculators
Insurance Radar in numbers
Compulsory and voluntary insurance
Which insurance is mandatory by law and which is voluntary. General information – check your own situation with the authority or your insurance company.
| Insurance | Mandatory? | For whom / when | Source |
|---|---|---|---|
| Motor insurance | Yes | The owner or holder of a motor vehicle registered for road use. A vehicle is in traffic also in yards, fields, forests and on ice. If the vehicle is not used, it can be deregistered from road use. | Motor Insurers' Centre |
| Motor insurance for a light electric vehicle | Yes, if the limit is exceeded | Rule of thumb: if a motorised device weighs over 25 kg or its speed exceeds 25 km/h, it needs motor liability insurance. | Motor Insurers' Centre 5.3.2026 |
| Snowmobile motor liability insurance | Yes | A snowmobile must always have motor liability insurance when driven. | Motor Insurers' Centre 2025 |
| YEL insurance | Yes, for the entrepreneur | For an entrepreneur whose earned income is at least 9 423 €/year (2026) and whose business has continued uninterrupted for at least four months. The contribution is 24,4 % of earned income. Owning a company alone is not sufficient grounds. | Finnish Centre for Pensions 2026 |
| TyEL insurance | Yes, for the employer | The employer insures its employees' pension cover, including a household as an employer. | Finnish Tax Administration (Verohallinto) |
| Occupational accident and occupational disease insurance | Yes, for the employer | Mandatory if the employer pays wages totalling over 1 200 € in a calendar year. | Finnish Tax Administration (Verohallinto) |
| Home insurance | No | Voluntary. In an apartment block you usually insure your movable property; in a detached house, the building as well. | FINE |
| Comprehensive motor insurance | No | Voluntary vehicle insurance; 49 % of surveyed households have it. | Finance Finland 2025 |
| Boat insurance | No | Unlike motor insurance, boat insurance is not compulsory. | Taloustaito 20.5.2026 |
| Travel insurance | No | Voluntary. Kela's European Health Insurance Card is free of charge, but it does not replace travel insurance – they complement each other. | Kela |
| Life insurance | No | Voluntary; 26 % of surveyed households have life insurance taken out in case of death. | Finance Finland 2025 |
What home insurance typically covers and what it does not
General principles from FINE's guidance. Coverage always depends on the terms and scope of your own insurance, so check them in your own policy document.
| Subject | Typically | Notice | Source |
|---|---|---|---|
| Comprehensive home insurance | Covers sudden and unforeseeable damage | A narrower insurance only covers events named in the terms | FINE: Home insurance |
| Fire | Belongs to safety | After a fire, temporary accommodation costs can also be compensated, subject to the terms | FINE: Home insurance |
| Damage caused by thunder | Belongs to safety | For example damage to electrical appliances, subject to the terms | FINE: Home insurance |
| Leak from a household appliance or a pipe | Belongs to safety | Water that has leaked from the junction of the piping and the structure, and failure of the waterproofing, are generally not covered | FINE: Frequently asked questions |
| Age and condition of the property | Affect the compensation | Age deduction is often 8–15 % a year from the second year of use onwards | FINE: Frequently asked questions |
| Loss or forgetting | Not reimbursed | Items forgotten and later stolen are usually not compensated | FINE: Frequently asked questions |
| Damage caused by insects | Not reimbursed | Typically excluded from coverage | FINE: Frequently asked questions |
| Neglecting protection instructions | May reduce the compensation | The instructions are in the insurance terms | FINE: Home insurance |
| Liability insurance | Compensates another person for damage | When the insured person is liable for compensation for personal injury or damage to property caused to another; also covers family members living in the same household | FINE: Liability and legal expenses insurance |
| Legal expenses insurance | Pays out in certain cases | Legal and court costs in disputes defined in the terms | FINE: Liability and legal expenses insurance |
| Deductible | Deducted from the compensation | The amount of the deductible is shown in the insurance policy | FINE: Frequently asked questions |
If the claim is rejected: the appeal chain
Proceed step by step. The decisions of FINE and the boards are recommendations and do not bind the parties, but in 2025 the companies followed them in about 94 % of cases.
| Step | What is done | Deadline / duration | Source |
|---|---|---|---|
| 1. Claim to the insurance company | Claim compensation from your own insurer | Within one year of learning about the possibility of compensation, and at the latest within 10 years of the damage | FINE: guide |
| 2. Ask the company for a new assessment | First contact your own insurance company; the company's own rectification procedure is usually the fastest | – | FINE: Frequently asked questions |
| 3. Advice from FINE | Free telephone and postal advice on insurance matters | Most matters are resolved straight away through phone advice | FINE: Frequently asked questions |
| 4. FINE's office procedure or the Insurance Complaints Board | Written handling of a dispute, free of charge; results in a recommended decision | For voluntary insurance 3 years from receiving the claim decision; processing takes 4–7 months on average (office) or 6–9 months (board) | FINE: Frequently asked questions |
| 5. Consumer Disputes Board (alternative) | Gives settlement recommendations in disputes between consumers and businesses, including in insurance matters | The board gives no advice – advice is available from consumer advisory services | Consumer Disputes Board |
| 6. District court | Action against an insurance company; can become expensive | 3 years from receiving written notice of the company's decision and the time limit (Insurance Contracts Act section 74) | FINE: resolution recommendation VKL 487/14 |
| Exception: motor insurance | Appealing against a motor liability insurance compensation decision | 1 year from the decision being issued | FINE: Frequently asked questions |
| Exception: statutory accident insurance | Appealing against a work accident compensation decision | 30 days from receiving the compensation decision | FINE: Frequently asked questions |
Source: FINE Finnish Financial Ombudsman Bureau; Consumer Disputes Board; Insurance Contracts Act 543/1994
Consumer rights under the Insurance Contracts Act
Key rules of the Insurance Contracts Act (543/1994) concerning consumers' voluntary insurance. For general information – the exact terms are in your own policy document.
| Situation | What the law says | Source |
|---|---|---|
| Cancelling an insurance policy | The policyholder can cancel the policy to end at any time during the insurance period, not only at the end of the period. | Insurance Contracts Act, section 12 |
| Insurance premium goes unpaid | An insurer can cancel a policy, but it ends no earlier than 14 days after the cancellation notice is sent. The notice must state the reason for the termination. | Insurance Contracts Act, section 14 |
| Payment of compensation | The compensation must be paid no later than one month after the company has received sufficient documentation. Penalty interest is paid on delayed compensation. | Insurance Contracts Act, section 70 |
| Information when taking out insurance | An insurance applicant must answer the insurer's questions truthfully. Incorrect information can reduce the compensation or lead to the policy being cancelled. | Insurance Contracts Act, sections 22–24 |
Statutory contributions for entrepreneurs and employers 2026
Key figures for the Self-Employed Persons' Pension Insurance (YEL) and employers' social insurance contributions in 2026. An employer's actual TyEL and accident insurance premium depends on the company's size, industry and insurer.
| Fee or limit | 2026 | Notice | Source |
|---|---|---|---|
| YEL contribution | 24,4 % of YEL income | Regardless of age | ETK |
| YEL, new entrepreneur | 19,032 % | 22 % discount for four years | Elo, ETK |
| Lower limit of YEL work income | 9 423,09 €/v | Insurance obligation once activity has lasted continuously for 4 months | Elo |
| Upper limit of YEL work income | 214 000 €/v | Elo | |
| Unemployment security threshold | 15 481 €/v | YEL work income with which an entrepreneur can receive earnings-related unemployment security | Elo |
| Average TyEL contribution | 24,4 % of salary | Employee 7.30%, employer on average 17.10% | ETK |
| Temporary employer's TyEL contribution | 25,85 % | Elo | |
| Unemployment insurance contribution | Employer 0.31% / 1.23%, employee 0.89% | Employer's higher contribution on the portion of payroll exceeding €2,509,500 | ETK, Elo |
| Employer's health insurance contribution | 1,91 % | ETK | |
| Occupational accident and occupational disease insurance | The fee varies by company | Mandatory when wages over 1 200 € are paid in a calendar year | ETK, Finnish Tax Administration |
| The entrepreneur's own accident insurance | Voluntary | YEL work income as the basis for the fee and benefits | Federation of Finnish Enterprises |
Save time with ready-made templates
Free tool available to download with a free account. Larger tools as a one-off purchase, no subscription: files immediately after payment.
 Free tool
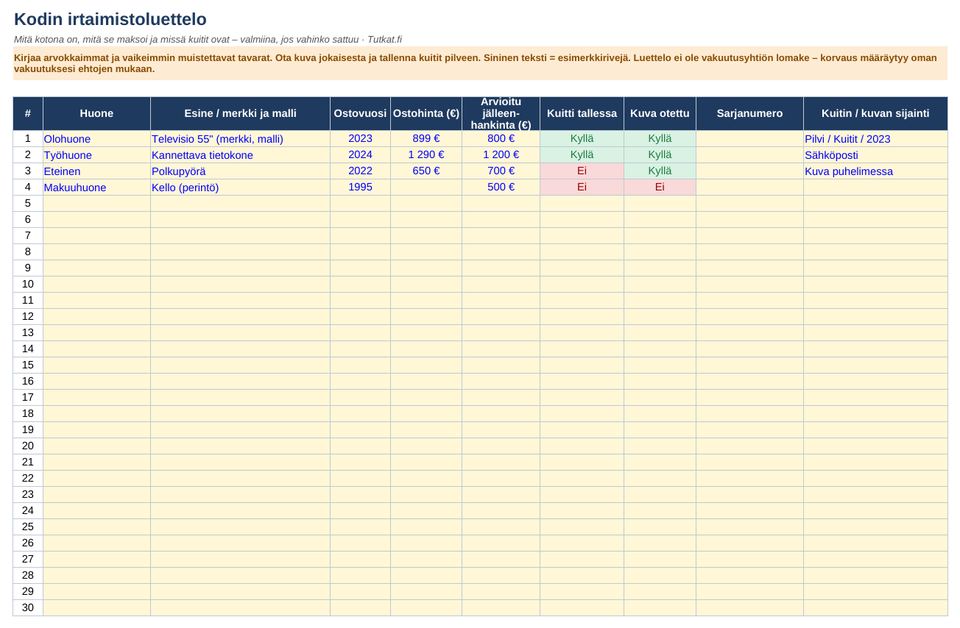
Home contents inventory
List your household goods, receipts and photos in advance in case of damage, and check the sum insured of your home insurance.
- A list of 100 items by room
- Receipt and photo status, missing ones highlighted
- Values by room and comparison with the insured amount
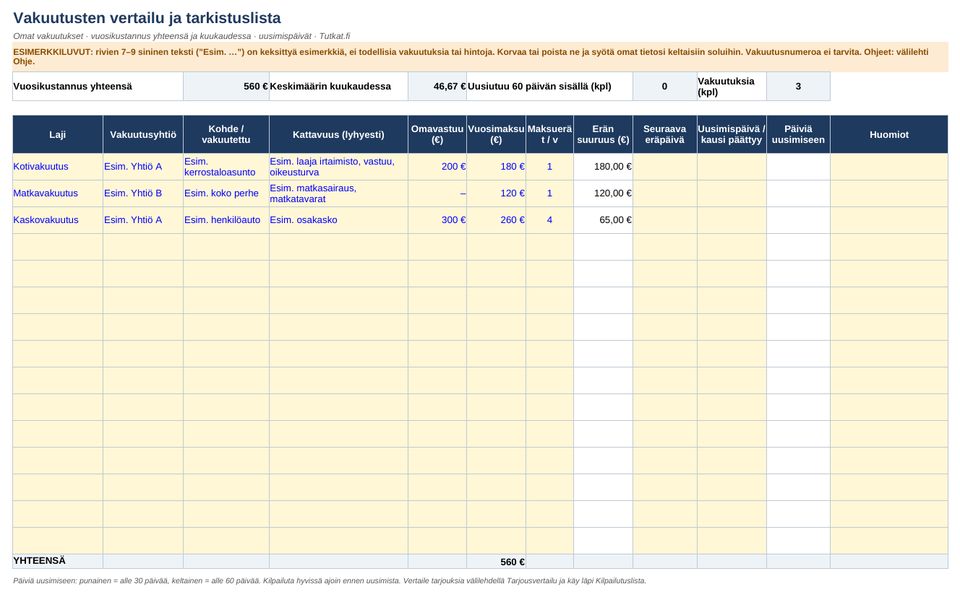
Insurance comparison and checklist
Your own insurance policies in one place, comparison of offers and annual cost.
Households
1,90 € incl. VATBuy 1,90 €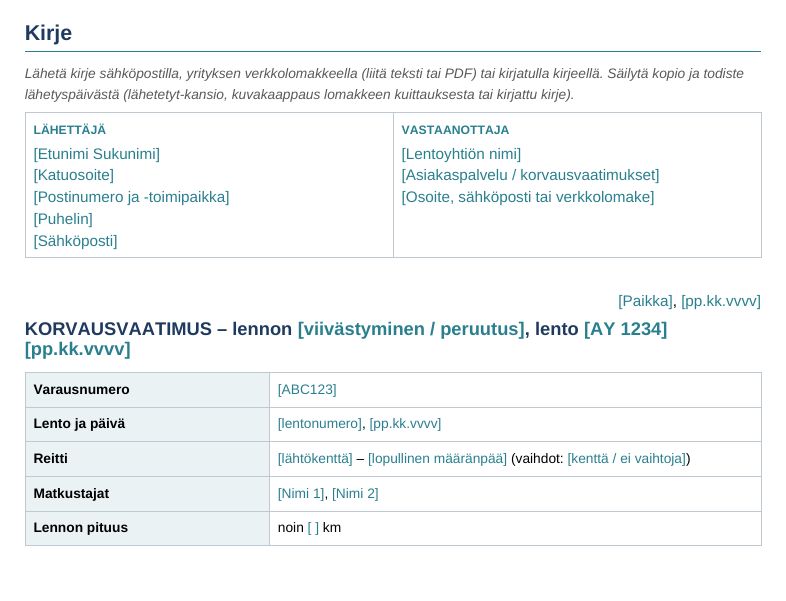
Complaint and compensation claim templates
Five ready-made letters: flight delay, lost luggage, faulty product, service defect and insurance decision.
Consumers
2,90 € incl. VATBuy 2,90 €Read before you decide
Compulsory insurance in Finland: which you must take and which you need not
Motor insurance, YEL, TyEL and occupational accident insurance are statutory. See who they apply to in 2026 and what follows from neglecting them.
Read the guide →Home insurance and claiming compensation: what to do if compensation is denied
What home insurance covers, how to claim compensation for damage and how to appeal a negative decision. Deadlines and free help from FINE Finnish Financial Ombudsman Bureau.
Read the guide →YEL 2026: contribution, work income and the new-entrepreneur reduction
The YEL contribution in 2026 is 24.4% of work income for everyone and 19.032% for new entrepreneurs. See the work income limits, the insurance obligation and how work income is determined.
Read the guide →Deadlines and dates
Insurance Radar reminds its subscribers of these by email.
- Employment pension contributions unchanged in 2027
According to the agreement of the labour market central organisations, the TyEL contribution in 2027 averages 24.4%, of which the employee's share is 7.30%; the YEL contribution is 24.4%. The Ministry of Social Affairs and Health confirms the contributions in November.
Source - Unemployment insurance contributions 2027
The Employment Fund proposes lowering the contributions: 0.26% and 1.04% for the employer, 0.74% for the employee. The final contributions are confirmed in autumn 2026.
Source - Solvency II changes affecting insurers enter into force
Most of the amendments to the Insurance Companies Act enter into force: among other things, a new class of small and non-complex insurance undertakings and sustainability and liquidity risk management plans. The amendments concern companies, not directly customers' insurance terms.
Source
No upcoming dates right now.
Frequently asked questions: Insurance Radar
Is home insurance mandatory?
The law does not oblige you to take out home insurance; it is voluntary. It is nevertheless the most common voluntary insurance: in Finance Finland's 2025 insurance survey, 84 % of respondents' households said they have home insurance.
What do I do if the insurer rejects my claim?
First ask your own insurance company for a new assessment. If you still disagree, contact FINE, the Finnish Financial Ombudsman Bureau, which advises free of charge and can handle the matter as a dispute. A recommendation for a decision does not bind the company, but in 2025 companies followed recommendations in about 94% of cases. The final step is a claim in the district court.
How much time do I have to appeal a compensation decision?
For voluntary insurance, such as home, car and travel insurance, you have three years from when you received written notice of the decision. For motor liability insurance the appeal period is one year, and for statutory accident insurance only 30 days.
What happens if you forget your car's motor liability insurance?
The Motor Insurers' Centre charges an uninsured fee, which can be at most three times the amount of the insurance premium. In 2025 the fee was imposed on about 32 000 vehicles. For a lapse of a few days on a passenger car the fee is about 70 euros, but for a long lapse it can rise to over 10 000 euros. If you do not use the car, it can be deregistered from road use.
Does Kela's European Health Insurance Card replace travel insurance?
It does not replace it. Kela stresses that the card and travel insurance complement each other. The card is free of charge and entitles you to public, medically necessary care in EU and EEA countries. Travel insurance covers, for example, the costs of private care in accordance with its terms. A card ordered from 15.1.2026 onwards is valid for five years.
Does an entrepreneur need to take out YEL insurance?
Yes, if your work income is at least €9,423 per year (2026) and your business has been operating continuously for at least four months. Merely owning a company is not enough; you must also work in it. If you hire employees, you also need TyEL pension insurance and accident and occupational disease insurance when you pay wages of more than €1,200 in a calendar year.
How do I check that a provider of insurance is reliable?
Insurance intermediaries must be registered. On the website of the Financial Supervisory Authority (FIN-FSA) you can check whether an intermediary is registered. Insurance Radar does not sell or broker insurance, nor does it recommend companies or products.
What does underinsurance mean?
Underinsurance means that property is insured for less than its actual value. If, for example, the sum insured for contents under a home insurance policy is too low, the compensation may fall short of the amount of the damage. It is worth checking the sum insured, for example after moving, renovating or making large purchases.
How much is the YEL contribution in 2026?
The YEL contribution is 24.4% of the confirmed YEL work income regardless of age. A new entrepreneur receives a 22% reduction for four years, bringing the contribution to 19.032%. The lower limit of YEL work income is €9,423.09 and the upper limit €214,000 per year. The pension provider reviews the work income every three years.
How much is the TyEL contribution and who pays it?
The TyEL contribution in 2026 averages 24.4% of pay. The employee's share of 7.30% is withheld from pay, and the employer's share averages 17.10%. The contribution for a temporary employer is 25.85%. For 2027 it has been agreed that the contribution will stay unchanged.
When must an employer take out accident insurance?
Statutory workers' compensation and occupational disease insurance is mandatory when the employer pays wages totalling more than 1,200 euros in a calendar year. The premium varies by insurer and by the risk of the work.
Does statutory accident insurance cover the entrepreneur themselves?
No. The employer's accident insurance covers employees. An entrepreneur insured under YEL can take out voluntary accident insurance, whose premium and benefits are based on the YEL work income. In Kela's sickness allowance, the waiting period for an entrepreneur insured under YEL is only the day of falling ill.
How to use the information
- Review your insurance cover from time to time and always when your life situation changes or you accumulate assets. Compare quotes: in a comparison by Kuluttaja magazine, home insurance prices have differed by as much as €600 a year, but always look at the content as well as the price.
- Check your policy document for deductibles and overlaps: the same risk may be insured twice, for example in a credit card's travel insurance and a separate travel insurance. A credit card's travel insurance is often narrower.
- Make sure your home insurance includes liability and legal expenses cover and that the maximum compensation matches the current value of your property.
- Claim compensation in good time: usually within a year of learning about your right to compensation. If you disagree with a decision, first ask the insurer for a new assessment and then contact FINE – the service is free of charge.
- Take Kela's European Health Insurance Card with you on a trip to Europe, but remember that it does not replace travel insurance. An illness that began before the trip is generally not compensated as a travel illness.
- Estimate the YEL work income according to the value of your work input: besides your pension, it determines Kela's daily allowances and whether you exceed the threshold for earnings-related unemployment security (15 481 €/year in 2026).
- A starting entrepreneur gets a 22 % discount on the YEL contribution for four years. Check that the discount shows on your invoice.
- Take out statutory accident insurance before the wages paid exceed 1 200 euros in a calendar year.
- As ancillary costs of salary, budget at least the employer's TyEL share (on average 17.10 %), the sickness insurance contribution of 1.91 % and the unemployment insurance contribution of 0.31 %, plus accident insurance.
Useful links
Get the Insurance Radar digest by email
Every Monday or once a month: the most important figures and the next deadlines. Free of charge, and you can cancel at any time.
Related radars
Sources (32)
- Finance Finland: Insurance Survey 2025 (publication slides)
- FINE: Scams and insurance disputes increased contacts to FINE in 2025 (20.2.2026)
- FINE: Frequently asked questions – FINE and financial services (time limits, processing times)
- FINE: Home insurance
- FINE: Frequently asked questions – home, property, animal and general property insurance
- FINE: Liability and legal expenses insurance
- FINE: Slip-and-fall injury – who pays and how to claim compensation? (time limits)
- FINE: resolution recommendation VKL 487/14 (Insurance Contracts Act section 74)
- FINE: Insurance at different stages of life – good to know
- FINE: Travel insurance does not cover everything (5.5.2026)
- Motor Insurers' Centre: An uninsured vehicle can mean a bill of thousands of euros at worst (5.3.2026)
- Motor Insurers' Centre: Neglecting the insurance obligation
- Motor Insurers' Centre: The obligation to insure a vehicle
- Motor Insurers' Centre: A snowmobile must have motor insurance whenever it is driven
- Finnish Centre for Pensions: The ABC of self-employed pension cover 2026
- Finnish Tax Administration: Contributions of a household employer
- Kela: European Health Insurance Card
- Consumer Disputes Board
- Taloustaito: Skimping on boat insurance can get expensive (20.5.2026)
- Verkkouutiset / Kuluttaja magazine: Home insurance prices differ by as much as 600 euros (29.7.2020)
- Finnish Government: Changes to starting and carrying on insurance and reinsurance business (25.6.2026)
- Financial Supervisory Authority: Insurance intermediary register
- Finnish Centre for Pensions: Earnings-related pension contributions
- Finnish Centre for Pensions: Statutory social insurance contributions in Finland 2026
- Elo: Social insurance contributions 2026
- Finnish Centre for Pensions: Effects of the government's mid-term review on the reform of the Self-employed Persons' Pensions Act (4/2026)
- Pension Negotiation Group: Earnings-related pension contributions in 2027 (6.10.2026)
- Employment Fund: Board of Directors proposes lowering unemployment insurance contributions (27.8.2026)
- Finnish Workers' Compensation Center: The number of occupational accidents will fall in 2026 (25.9.2026)
- Finance Finland: Willingness to take voluntary insurance has fallen (22.9.2025)
- Federation of Finnish Enterprises: Illness and accidents
- Federation of Finnish Enterprises: Entrepreneur's accident insurance
The information has been compiled from public sources on 6.10.2026. Always check the current terms from the original source. The information is not investment, loan or legal advice.